David did an excellent job at explaining to us that financially we are doing just fine at this time to be okay with our retirement, which really put our minds at ease. He explained what they can do for us going forward to help us continue on the right path.
We do more than Medicare.

Will your money last as long as you do?
RETIREMENT INCOME PLANNINGYou picked up our flyer in the office. This is the rest of the story, with room for the details.
You worked hard and saved for years. Now your savings need to pay you. We build a clear plan that shows how much income you may have, and how long it may last.
We help bring it all together
Each line on the flyer is a decision, and every one of them touches the others. Here is what each one means for you, in plain English.
Social Security timing
You can start at 62 or wait as late as 70, and the monthly check grows the longer you wait. Start early and the reduction generally stays with you, so we weigh your health, your work, and what your spouse would keep.
Read: Is Your Social Security Right? →Pensions
Lump sum or monthly check? Single life or a survivor option? The choice is usually final, so we run the numbers with both of you in the room.
Read: What Changed About Retirement →Monthly retirement income
We start with what a normal month costs you. Then we line up where every dollar of that month will come from.
Read: What Is Retirement Income Planning (And Why Most Retirees Skip It) →Income that doesn't ride the market
Some of your bills should be covered by income that arrives whether or not the market cooperates. An annuity can contract to pay you for life, backed by the company that issues it. It is one tool, not the answer for all of your money.
Read: Not All Annuities Are Created Equal →Tax-smart withdrawals
Which account you draw from first can change your tax bill for years. Required minimum distributions will eventually set part of that schedule for you, so we plan the years before they start on purpose.
Read: Putting It All Together: A Tax-Smart Way to Draw Your Retirement Paycheck →Roth conversions
You pay income tax on what you convert, in the year you convert it. Done in the right years, it can mean lower taxes later for you and for your heirs.
Read: The Roth Conversion Playbook →401(k) and IRA rollovers
Ask for a direct rollover and no taxes are withheld. If the check is made out to you, taxes can be withheld and you have 60 days to finish the move.
Read: Should You Roll Over Your 401(k)? What Scottsdale Retirees Need to Consider →Medicare surcharges (IRMAA)
Medicare sets these surcharges from your tax return from two years ago. A large withdrawal or a Roth conversion today can raise your Part B and Part D premiums later, so we plan around it.
Read: The IRMAA Trap →Income projections
A year-by-year picture of what comes in and what goes out, so you can see how long your money may last, built on assumptions you can read and question.
Read: You Have Enough Money to Retire. So Why Can't You Pull the Trigger? →Watch before you meet us
A few minutes from our team on turning what you saved into income you can live on.
He has a healthy balance and thinks he is fine. David Schaeffer and David Edge explain why that is not a plan.
Meet David Schaeffer
Don't run out of money before you run out of time.David Schaeffer
David founded American Retirement Advisors and has sat with families through these decisions thousands of times. He lays your money out in his Three Colors of Money, so you can see which dollars are safe, which pay you, and which are working for growth. Then he shows you the whole plan on one page.
How it works
or call 602-281-3898
Keep exploring
Go deeper on any line from the flyer, at your own pace.
Read
Service · September 8, 2026Retirement incomeHow David turns Social Security, pensions, rollovers, and savings into a steady monthly paycheck, explained in plain English.Read →
Guide · April 22, 2026Is Your Social Security Right?Check your earnings record, fix mistakes before they cost you, and weigh when to claim. A downloadable guide.Read →
Guide · April 21, 2026The IRMAA TrapWhy a good income year can raise your Medicare premium later, how the lookback works, and how to appeal.Read →
Guide · June 1, 2026Required Minimum DistributionsDavid Schaeffer explains where the RMD rule came from, how the amount is figured, and the traps to plan around.Read →
Article · July 2, 2026Putting It All Together: A Tax-Smart Way to Draw Your Retirement PaycheckWhich account to draw from first, and how steering your taxable income each year keeps more of your paycheck.Read →
Article · May 15, 2026You Have Enough Money to Retire. So Why Can't You Pull the Trigger?Plenty saved but afraid to spend it? A written income plan is what gives you permission to enjoy it.Read →
Guide · May 5, 2026Not All Annuities Are Created EqualThe main annuity types side by side in plain language, so you know what you are looking at before you decide.Read →
Article · May 21, 2026Your Monthly Budget Is Probably Wrong. Here's How to Fix It.An income plan starts with what you really spend. Here is how we go through statements line by line.Read →
Guide · May 14, 2026What Changed About RetirementDavid Schaeffer on how pensions gave way to the do-it-yourself paycheck, and why retirement taxes feel different now.Read →Listen
Watch
A business owner sold his company and his Medicare premiums jumped. David and Greg Frantz explain IRMAA and what to do next.
Quick answers, under a minute
What families say
After thorough initial discovery and diligent listening, David provided a comprehensive overview of what could be done to strengthen and assure a healthy retirement plan for my wife and I. I confidently felt that he was engaged with the client in front of him and NOT promoting a cookie cutter presentation.
He was very prepared for our meeting, and remembered everything we had discussed from our visit when my husband was turning 65, almost 2 years ago. We have complete confidence in David.
Real reviews from real clients, shown as written except for length. Reviewer names are first name and last initial. Nobody is paid for a review.
Straight answers
Do I need to be a Medicare client to ask about income?
No. Many families meet us through Medicare, and plenty meet us the other way around. If we already help you with Medicare, your advisor knows part of your story, and your income plan builds on it.
What happens when I request an appointment?
Adam Frye from our client care team calls you to find a time that works, in our Scottsdale, Mesa, or Las Vegas office or on Zoom. He asks a few questions first, so your advisor is ready when you sit down.
What should I bring?
Recent statements for your retirement and savings accounts, your Social Security estimate, any pension paperwork, and a rough idea of what a normal month costs. If something is missing, come anyway.
Do I have to move my money to work with you?
No. The first meeting is Discovery Day, not decision day. You leave with a clear picture of where you stand and decide what to do when you are ready.
Book your retirement income review
Tell us how to reach you and we will call to set a time. Rather talk now? Call 602-281-3898.
602-281-3898Send Us a Request
We typically respond within one business day.
We do more than Medicare.
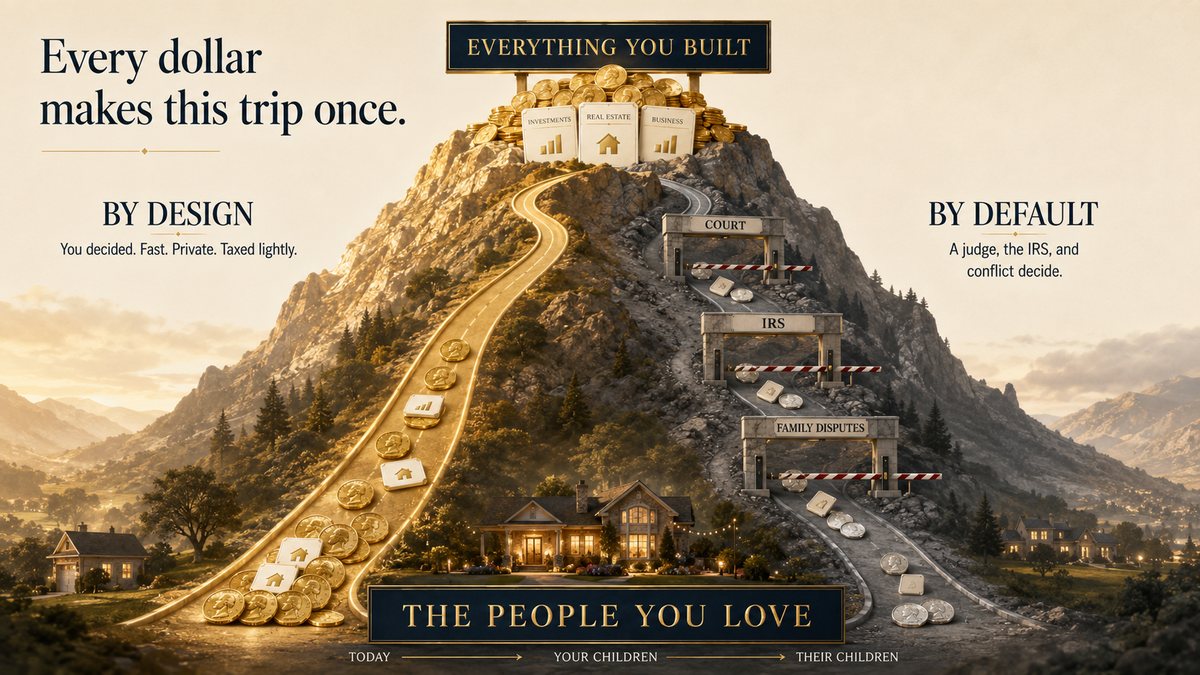
Inheritance planningDon't leave your family guessing. Four guided sessions with David, the Beneficiary Box™, and a family meeting.See how it works →
Generational wealth strategiesFor larger estates and business owners. Pass it on by design, with your attorney and CPA working from one plan.See how it works →