We do more than Medicare.

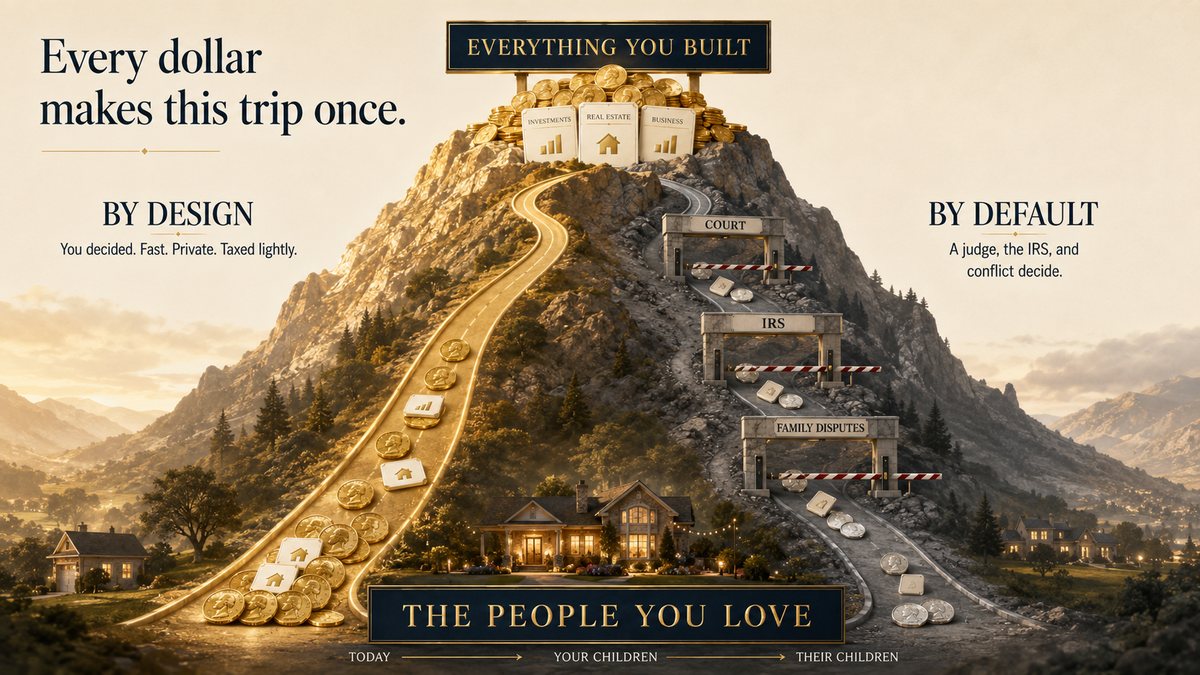
Illustration: a golden road marked By Design carries everything you built down the mountain to the people you love, while a gray road marked By Default passes through court, the IRS, and family disputes

Pass it on by design, not by default.

GENERATIONAL WEALTH STRATEGIES

You picked up our card in the office. Here is the fuller picture behind it.

In 2026 the federal estate tax exclusion is $15,000,000 per person. The amount above it can be taxed at rates up to 40%, and a revocable living trust, by itself, does not lower that.

American Retirement Advisors
The rest of the flyer

What we look at

Generational wealth is the advanced end of our inheritance work. We plan and coordinate. Your estate attorney and your CPA execute.

Federal estate tax

The exclusion is $15,000,000 per person for 2026, and taxable gifts you made during life count against it. We show you where your estate stands against that line today, and where it is heading.

Read: The Nine-Month Problem That Forces Families to Sell What They Love →

Trusts

A revocable living trust can help your family avoid probate. Moving money out of your taxable estate is a different job, usually done with gifts or irrevocable trusts your attorney drafts.

Read: Understanding Revocable Trusts →

Business owners

A will does not create a buyer, a price, or a successor. We map the exit alongside the rest of your estate.

Listen: When the Problem Isn't Growth, It's Coordination →

Life insurance

A policy you own counts in your estate. Owned the right way, often through a trust, it can stay outside your estate and give heirs cash when they need it.

Listen: Your Own Life Insurance Could Be Adding to Your Tax Bill →

Charitable giving

A charitable remainder trust can pay you income for life or a set term, then leave the rest to charities you choose. It is irrevocable, so it takes careful planning.

Read: Layering a Windfall Onto an Already-Full Plan →

Step-up in basis

Property your heirs inherit generally takes a new basis at its value on the date of death. Giving it away during life can pass along your old basis instead, so timing matters.

Read: Passing On the House: Step-Up in Basis, Gifting Rules, and the Estate Tax Most Families Will Not Pay →

Inherited IRAs

Most adult children who inherit an IRA must empty it within 10 years, often in their own peak earning years. Where the money sits today shapes what they keep.

Read: The Ten-Year Tax Bomb: What Your IRA Looks Like From Your Kids' Side →

Gifting

In 2026 you can give up to $19,000 to each person you choose, and gifts at or under that amount generally are not taxable gifts. Planned on purpose, gifting lets you watch the money help while you are here.

Read: Giving While You're Alive to Watch It →

Trump Accounts

A new kind of IRA for children under 18. Grandparents can contribute, so we show you where one fits beside the rest of your gifting.

Generational wealth strategies, explained →
Watch

Watch before you meet us

Short answers to the questions families ask about passing on what they built.

Building wealth and passing it on follow different rules. Jason Tweet explains why the handoff needs its own strategy.

Who you will sit with

Who you'll sit down with

A segmented plan or a siloed plan isn't a plan.Jason Tweet

Jason Tweet leads our generational wealth strategies. He works alongside David Schaeffer, who founded American Retirement Advisors. Together they look at the whole picture, not one account at a time, then quarterback with your attorney and your CPA so every document says the same thing.

How it works

How our process works for you

OrganizeWe gather the whole picture on one page: accounts, titles, trusts, policies, business papers, and every beneficiary form.
ReviewJason and David find what is working, what is exposed, and where your estate stands against the federal exclusion. You get it in plain English.
CoordinateWe bring your estate attorney and your CPA to one plan. If you don't have one, we can introduce you to professionals we work with.
ImplementYour attorney drafts, your CPA files, and we keep everyone on schedule. Then we review it with you every year.

Keep exploring

More on estate tax, trusts, inherited IRAs, and passing on a business.

Read

Service · September 8, 2026Generational wealth strategiesHomes, accounts, businesses, and values handed to the next generation without losing them to taxes, probate, or confusion.Read →Article · June 25, 2026The Nine-Month Problem That Forces Families to Sell What They LoveWhen a large estate owes federal tax, the bill comes due fast and in cash. How families plan so nothing gets sold.Read →Guide · August 13, 2026Understanding Revocable TrustsWhat a living trust can and cannot do, including why it does not, by itself, reduce estate tax.Read →Article · June 26, 2026Your Own Life Insurance Could Be Adding to Your Tax BillA policy you own can quietly add to the estate tax you hoped to solve. How ownership through a trust changes that.Read →Article · July 5, 2026Passing On the House: Step-Up in Basis, Gifting Rules, and the Estate Tax Most Families Will Not PayGive the house now or leave it later? The tax code treats those very differently. Here is the difference.Read →Article · July 14, 2026The Ten-Year Tax Bomb: What Your IRA Looks Like From Your Kids' SideWhat your IRA looks like from your kids' side, and why the inherited IRA clock can land in their highest-earning years.Read →Guide · April 27, 2026The Roth Conversion PlaybookHow converting on your own schedule can shrink required withdrawals and leave heirs a lighter tax bill.Read →Article · June 15, 2026When the Problem Isn't Growth, It's CoordinationOnce you have enough, the biggest risk is the gaps between advisors who never talk. Why coordination matters most.Read →Article · June 13, 2026The Hardest Part of Passing On Wealth Isn't the MoneyThe families who keep wealth are the ones who prepared the people, not just the paperwork.Read →Article · June 18, 2026Giving While You're Alive to Watch ItMost wealth passes when heirs need it least. The case for giving while you are here to watch it help.Read →

Listen

Passing On the House: Step-Up in Basis, Gifting Rules, and the Estate Tax Most Families Will Not PayHow the tax basis on a home resets at death, and the estate tax rules most families never hit.Listen · 16:26 · Jul 5, 2026 →Inherited IRA Rules, Step-Up in Basis, and What Your Kids Actually Receive When Everything Passes to ThemWhat children actually receive from an inherited IRA once the newer distribution rules apply.Listen · 19:17 · Jul 9, 2026 →The Ten-Year Tax Bomb: What Your IRA Looks Like From Your Kids' SideWhy an inherited IRA can create a bigger tax bill for your children than most people expect.Listen · 18:11 · Jul 14, 2026 →The Nine-Month Problem That Forces Families to Sell What They LoveWhy families sometimes must sell a business or property quickly just to pay an estate tax bill.Listen · 16:02 · Jun 25, 2026 →Your Own Life Insurance Could Be Adding to Your Tax BillHow owning your own life insurance policy can unexpectedly increase your taxable estate.Listen · 15:54 · Jun 26, 2026 →Be Your Own Bank: The Cash Value Most People Never TouchHow the cash value inside a life insurance policy can work for you while you are still living.Listen · 15:14 · Jun 22, 2026 →How to Give the Grandkids Money Now, and Watch It MatterWhy giving money to grandchildren now can matter more than waiting to leave it later.Listen · 20:01 · Aug 29, 2026 →When the Problem Isn't Growth, It's CoordinationWhy wealthy families often need better coordination among advisors more than better investment returns.Listen · 14:45 · Jun 15, 2026 →

Watch

Generous people often give the most expensive way. David shows how giving from an IRA or appreciated stock can work better.

Quick answers, under a minute

What clients say

What families say

★★★★★

After thorough initial discovery and diligent listening, David provided a comprehensive overview of what could be done to strengthen and assure a healthy retirement plan for my wife and I. I confidently felt that he was engaged with the client in front of him and NOT promoting a cookie cutter presentation.
Mark P. · client
★★★★★

David did an excellent job at explaining to us that financially we are doing just fine at this time to be okay with our retirement, which really put our minds at ease. He explained what they can do for us going forward to help us continue on the right path.

Timothy P. · client
★★★★★

He was very prepared for our meeting, and remembered everything we had discussed from our visit when my husband was turning 65, almost 2 years ago. We have complete confidence in David.

Nancy G. · client

Real reviews from real clients, shown as written except for length. Reviewer names are first name and last initial. Nobody is paid for a review.

Questions people ask

Straight answers

We know you from Medicare. Do you really do this?

Yes. Medicare is often how families meet us. Income and inheritance are the rest of our work, and generational wealth is the advanced end of the inheritance side. You don't need to be a Medicare client to start.

Is this only for estates over $15 million?

No. Most of this work is about income tax on inherited accounts, probate, titles, and a business that needs a successor. Neither Arizona nor Nevada charges a state estate tax today, so the estate tax question here is a federal one.

We're married. Do we each get an exclusion?

Each spouse has one. When the first spouse dies, the unused part can pass to the survivor, but only if it is elected on a timely filed estate tax return. Your attorney and CPA handle that filing, and we make sure it is on the list.

Doesn't our living trust take care of estate tax?

Not by itself. A revocable living trust can help your family avoid probate, but what is in it still counts in your estate, because you can change or revoke it. Lowering estate tax takes different tools, drafted by your attorney.

What happens when I request an appointment?

Adam Frye from our client care team calls you to set a time with our team, in our office or on Zoom. Bring what you have. The will, the trust, and a list of accounts are a good start.

Request an appointment

Request a generational wealth conversation

Tell us how to reach you and we will call to set a time. Rather talk now? Call 602-281-3898.

602-281-3898

Send Us a Request

We typically respond within one business day.

Please enter your name.
Please enter a valid email address.
Please enter your phone number.
Loading...
Incorrect answer. Please try again.

Request Received!

Thank you for reaching out. A member of our team will be in touch with you shortly.

We typically respond within one business day.

If you need immediate assistance, please call us at (877) 220-1089.